
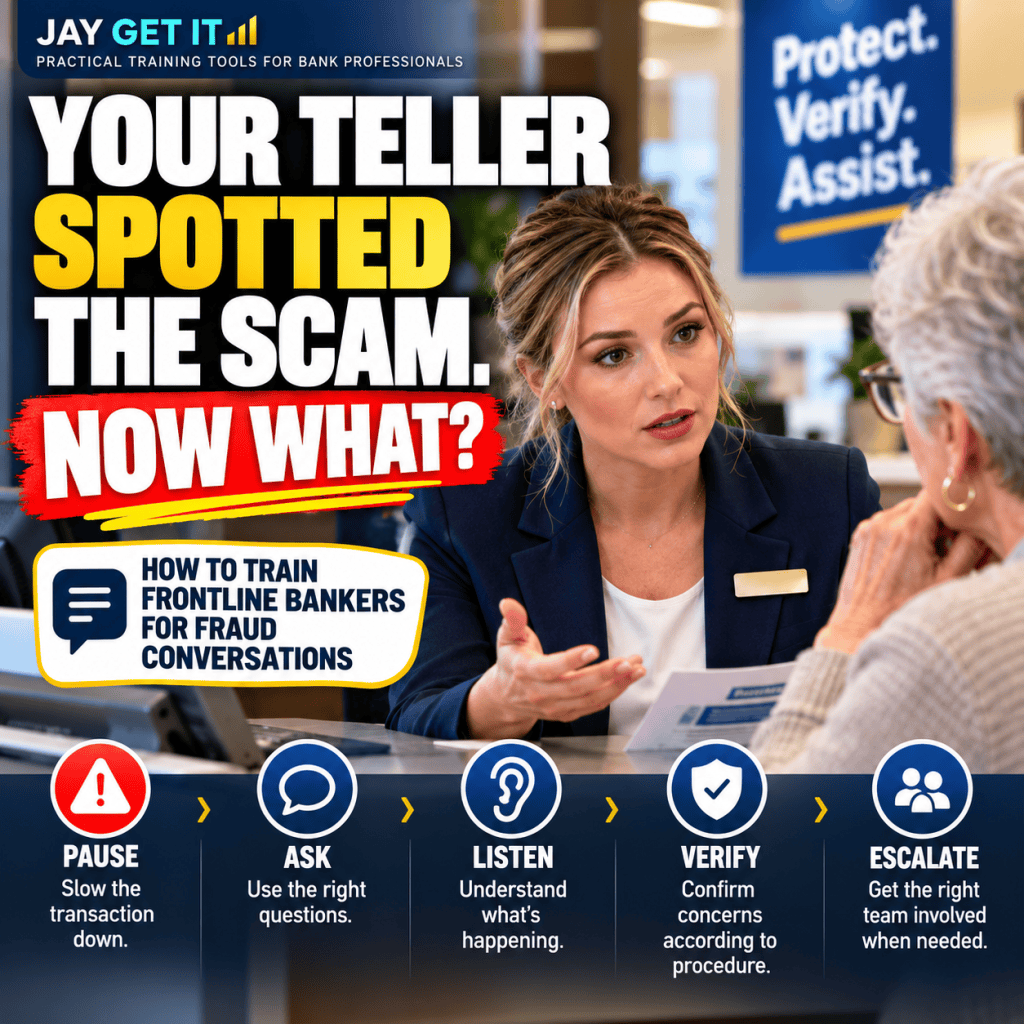
Your Teller Spotted the Scam. Now What? How to Train Frontline Bankers for Fraud Conversations
That title solves the real training gap: employees may recognize suspicious behavior, but they still need to know what to say, what to ask, when to pause, and when to escalate.
Recent data makes the topic timely. The FTC says consumers reported losing about $3.5 billion to imposter scams in 2025, with bank impersonators producing the highest reported losses among business impersonators.The FBI reported nearly $21 billion in cyber-enabled crime losses in 2025, while people over 60 reported approximately $7.7 billion in losses.
At the same time, frontline bankers are describing fraud work as a growing part of the job. In a September 2026 Reddit discussion, one banker described spending hours handling fraud cases, account replacements, and recovery-related work, while another said some days at a small bank can involve multiple new fraud cases.
Here is the publish-ready article.
Your Teller Spotted the Scam. Now What?
How to Train Frontline Bankers for Fraud Conversations
Most bank fraud training teaches employees what to look for.
An unusual wire.
A large cash withdrawal.
A customer being coached on the phone.
A sudden cryptocurrency investment.
A customer who cannot clearly explain who is receiving the money.
An urgent request to move funds immediately.
Those red flags matter.
But recognizing the red flag is only the beginning.
The harder moment comes next.
The teller looks at the customer and thinks:
“Something about this transaction does not feel right.”
The customer looks back and says:
“I know what I’m doing. Just send the money.”
Now what?
That is where fraud awareness becomes fraud conversation training.
And that distinction matters more than ever.
The FTC reported that consumers lost approximately $3.5 billion to imposter scams in 2025. Some of the costliest cases involved fake security alerts and bank impersonators convincing customers to move money in order to supposedly “protect” it. Federal Trade Commission
The FBI also reported nearly $21 billion in losses tied to cyber-enabled crime in 2025, with investment fraud and cryptocurrency-related losses among the largest categories. FBI
Your frontline employees are increasingly standing at the point where those scams become transactions.
The question is:
Are they trained to handle the conversation?
Fraud training often stops too early
A common training exercise sounds like this:
“Identify the red flags.”
That is useful.
But it does not fully prepare an employee for a real customer.
The American Bankers Association’s fraud-prevention training emphasizes helping frontline staff recognize common scams and fraud red flags. ABA
The next layer is turning that recognition into action.
BankersHub makes a similar point in its 2026 frontline scam-intervention guidance: employees may already recognize unusual withdrawals, urgent wires, emotional customers, or incomplete verification, but the real challenge comes after the warning sign appears. BankersHub
That is when the employee needs to decide:
- What should I ask?
- How direct should I be?
- How do I avoid embarrassing the customer?
- What if they become defensive?
- When do I bring in a supervisor?
- What if the customer insists on continuing?
Those are conversation skills.
And they require practice.
A red flag does not automatically mean fraud
This is one of the most important things to teach.
A large withdrawal is not automatically fraud.
An older customer sending money is not automatically a scam victim.
A customer being nervous does not automatically mean the transaction is illegitimate.
A new beneficiary is not automatically suspicious.
A red flag means:
Slow down. Gather more information. Follow your institution’s procedures.
It does not mean:
Accuse the customer.
That difference can determine whether the customer keeps talking to you or immediately shuts down.
The teller’s first job is often to slow the transaction down
Scammers rely heavily on urgency.
Customers may be told:
- “You have to do this right now.”
- “Don’t tell anyone.”
- “Your account is compromised.”
- “The bank is involved.”
- “Move the money before it disappears.”
- “Stay on the phone with me.”
- “Tell the teller the money is for something else.”
That urgency is valuable information.
When the customer is being pushed to move quickly, the banker may need to create a pause.
Not a confrontation.
A pause.
Try questions such as:
“Can I ask what the funds will be used for?”
“How did you first connect with the person receiving the money?”
“Have you met this person in person?”
“Did anyone tell you not to discuss the transaction with bank employees?”
“Did someone tell you your money was in danger unless you moved it?”
“Are you currently on the phone with the person asking you to send the money?”
The goal is not interrogation.
The goal is to give the customer room to explain what is happening.
Ask curious questions, not accusatory questions
Compare these two approaches.
Version 1
“This sounds like a scam.”
That may immediately make the customer defensive.
Now compare it with:
Version 2
“I want to understand what’s happening before we move forward. Can you tell me how you were contacted?”
The second approach keeps the conversation open.
Another example:
Instead of:
“You shouldn’t be doing this.”
Try:
“Before we complete this, I want to make sure you understand who is receiving the money and why.”
That distinction matters because scam victims often do not believe they are victims.
BankersHub notes that customers caught in scams may believe they are making a legitimate financial decision and may even have been coached on what to tell bank employees. BankersHub
If the employee starts by attacking the customer’s judgment, the customer may stop listening.
Teach employees what to say when the customer pushes back
This is where scenario-based training becomes valuable.
Consider this situation:
A customer wants to send $25,000 to someone they met online.
The teller asks questions.
The customer responds:
“This is my money. Why are you getting involved?”
What should the employee say?
Here are several professional options:
“You’re right that these are your funds. I’m asking a few questions because we sometimes see situations where customers are being pressured or misled, and I want to make sure you have all the information before we proceed.”
Or:
“I understand you want to complete the transaction. Before we move forward, I need to make sure I understand the purpose and follow the appropriate process.”
Or:
“My goal isn’t to make the transaction harder. I just want to make sure you’re comfortable with where the funds are going.”
The wording should always be adapted to your institution’s policies and escalation procedures.
But the training principle remains the same:
Give employees language before they need it.
What if the customer says, “I know this person”?
That should not automatically end the conversation.
Many scams depend on perceived relationships.
The customer may believe they are speaking with:
- A family member
- A romantic partner
- A bank employee
- A government agency
- A police officer
- A business executive
- A contractor
- An investment adviser
- A tech-support representative
The FTC says imposter scams were the most frequently reported fraud category in 2025, with more than one million reports. Federal Trade Commission
And modern impersonation can be extremely convincing.
BankersHub’s 2026 AI-fraud training materials warn that voice cloning, deepfakes, sophisticated phishing, and other AI-assisted tactics are making fraud harder to identify based only on whether something “looks real.” BankersHub
That changes the training question.
Instead of asking:
“Does this look fake?”
Employees increasingly need to ask:
“Can this be independently verified?”
“Pause and verify” is becoming more important
Suppose a customer says:
“My bank called me and said I need to move my money immediately.”
A safer next step may be independent verification.
That could mean following your institution’s approved procedures for confirming the situation through a trusted channel rather than relying on the phone number, email, text message, or website supplied by the person contacting the customer.
The principle is simple:
Do not verify the suspicious contact using information supplied by the suspicious contact.
That is especially relevant to bank impersonation scams.
A September 2026 Reddit post from a bank teller described customers receiving calls where the caller ID displayed the bank’s name. The teller said customers were asked for account or debit-card information and advised them to hang up and contact the branch independently. Reddit
Caller ID alone is not proof that the caller is legitimate.
Frontline fraud work is emotionally demanding
There is another side to this conversation that deserves more attention.
Fraud prevention is hard on employees too.
A September 2026 banking discussion described frontline staff spending significant portions of the day helping customers recover from fraud, replace accounts, restore access, and navigate the aftermath. The banker described the work as mentally draining. Reddit
That matters for training.
Employees are not just learning procedures.
They may be dealing with:
- Frightened customers
- Angry customers
- Embarrassed customers
- Customers who blame the bank
- Customers who refuse to believe they were scammed
- Customers who repeatedly return after additional losses
- Customers who are financially devastated
A good fraud-training program therefore needs more than transaction rules.
It should also teach employees how to remain professional when the conversation becomes emotional.
The employee should not become the customer’s opponent
This is a critical training concept.
If the interaction becomes:
Customer versus teller
the scammer often wins.
The better dynamic is:
Customer and teller versus the problem.
Instead of:
“You’re being scammed.”
Try:
“There are a few things about this situation that concern me. Can we review them together before you send the money?”
Instead of:
“This makes no sense.”
Try:
“I want to make sure I understand exactly what the other person told you.”
Instead of:
“You need to stop.”
Try:
“Before we continue, I’d like to slow this down and verify a few things with you.”
That language changes the teller from an obstacle into an ally.
When should the teller escalate?
Employees should not be expected to solve every suspicious situation alone.
Your institution should have clear guidance for when to involve:
- A supervisor
- Branch management
- Fraud operations
- Security
- Compliance
- Other approved internal resources
Employees should know:
Who do I call?
When do I call them?
What information should I provide?
Do I continue the transaction while waiting?
What do I tell the customer?
This is where vague fraud training creates problems.
An employee who knows 20 red flags but does not know the escalation process may still freeze in the moment.
Build fraud training around scenarios
Instead of another presentation full of bullet points, try giving your team realistic situations.
For example:
Scenario 1: The urgent bank call
A customer says someone from the bank told them their account was compromised and instructed them to withdraw $18,000 immediately.
Ask employees:
What concerns you?
Then ask the more important question:
What exact words would you say next?
Scenario 2: The online relationship
A customer wants to wire $30,000 to someone they met online six months ago.
They have never met in person.
The customer says the money is for an emergency.
Ask:
How would you start the conversation?
Scenario 3: The investment opportunity
A customer received instructions to move money into cryptocurrency for an investment promising unusually high returns.
Ask:
What questions would you ask before proceeding?
Scenario 4: The coached customer
The teller notices that the customer is reading answers from their phone and appears to be receiving instructions during the transaction.
Ask:
What would you do next?
That is where employees build confidence.
Not by memorizing a definition.
By practicing the conversation.
A simple Training Thursday exercise
Use this at your next branch huddle.
Give the team this prompt:
A long-time customer wants to withdraw $20,000 in cash. They are nervous, checking their phone repeatedly, and say the money is for “home repairs.” When you ask who the contractor is, they become defensive.
Then ask each person:
What would you say next?
Not:
“What red flags do you see?”
They will probably see the red flags.
Make them practice the words.
That is the training gap.
Fraud training should prepare employees for judgment, not just recognition
Fraud changes.
The scripts change.
The technology changes.
The payment methods change.
The social-engineering tactics change.
AI makes some fraud more believable and easier to scale. BankersHub
You cannot give frontline employees a script for every scam they will ever encounter.
But you can train repeatable habits:
Pause.
Ask.
Listen.
Verify.
Escalate.
Document according to procedure.
That creates an employee who can respond when the scam does not look exactly like the example in the training module.
Training Thursday takeaway
Recognizing a scam red flag is important.
But recognition alone does not protect the customer.
The frontline employee still needs the confidence to have the conversation.
That means training should answer:
What do I say?
What do I ask?
How do I slow the transaction down?
How do I avoid turning the customer against me?
When do I escalate?
Because when a customer is sitting across the desk insisting everything is fine, the employee cannot click “next” on a training module.
They have to respond.
And that is the skill worth practicing.
Join the conversation
For bank tellers, bankers, branch managers, trainers, and fraud professionals:
Does your fraud training teach employees what to SAY when they suspect a scam — or mostly what red flags to recognize?
And if you work on the frontline:
What is the hardest fraud conversation you regularly face?
- Romance scams?
- Investment scams?
- Bank impersonation?
- Large cash withdrawals?
- Cryptocurrency?
- Tech-support scams?
- Family emergency scams?
- Customers who refuse to believe they are being scammed?
Share your experience in the comments.
Someone training a new teller may learn from it.

