
Practical Bank Teller Training | Jay Get It
It’s almost closing time.
You’ve served customers, processed deposits, handled withdrawals, and counted cash throughout the day.
Now you’re balancing your teller drawer.
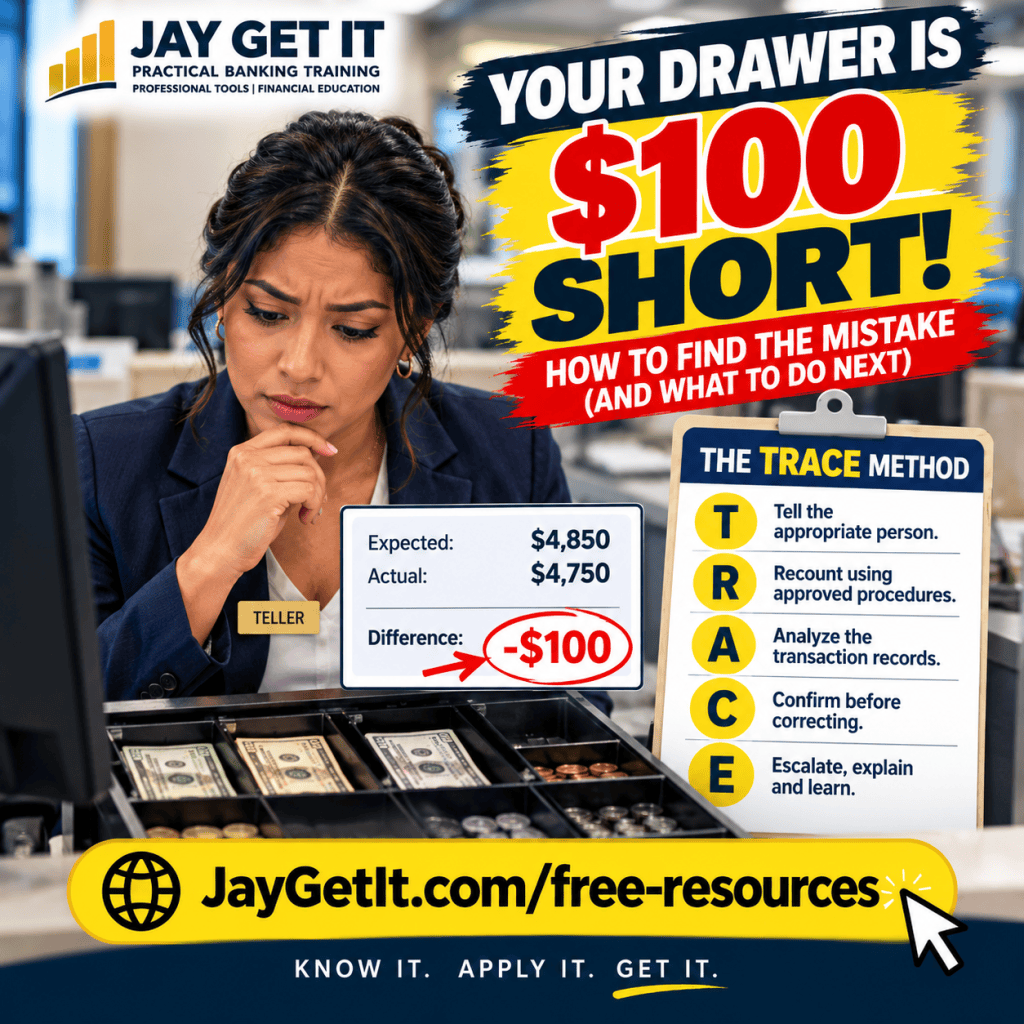
Your system says you should have $4,850.
Your physical cash count shows $4,750.
You’re $100 short.
Your first thought might be: Did I give someone too much money? Did I enter a transaction incorrectly? What happens if I can’t find it?
A cash drawer shortage can be stressful, especially for a new bank teller. But the most important thing isn’t how quickly you make the difference disappear.
It’s how accurately and honestly you handle it.
In this Teller Tuesday lesson, you’ll learn how to investigate a cash shortage, recognize common causes, and develop habits that help prevent future balancing errors.
Why Do Bank Teller Cash Drawers Come Up Short?
A cash shortage occurs when the physical cash in a teller’s drawer is less than the amount expected based on the institution’s transaction records.
Common causes include:
- Giving a customer more cash than the authorized withdrawal amount
- Recording a cash deposit for more than the amount actually received
- Miscounting bills, particularly during busy periods
- Entering the wrong transaction amount
- Recording a cash transfer incorrectly
- Mixing denominations or misreading a cash strap
- Missing or incorrectly recording a transaction
A shortage doesn’t automatically tell you which mistake occurred.
For example, a $100 shortage might result from one extra $100 bill being paid out. But it could also involve multiple errors or an incorrectly recorded transfer.
The shortage amount is a clue, not proof of the cause.
The $100 Teller Shortage: A Realistic Example
Imagine your teller drawer should contain $4,850, but your count shows only $4,750.
Earlier that day, you processed these transactions:
| Transaction | Recorded amount |
|---|---|
| Cash withdrawal | $600 |
| Cash deposit | $1,200 |
| Cash withdrawal | $900 |
| Cash transfer to vault | $2,000 |
You remember the $900 withdrawal because the customer was in a hurry.
Could you have accidentally handed out $1,000?
Possibly.
But don’t assume that’s what happened. You need to investigate using the records and procedures available at your institution.
Here’s a structured way to respond.
The 5-Step TRACE Method for Teller Cash Shortages
Use TRACE as a training reminder for the actions to take when your drawer doesn’t balance.
T — Tell the Appropriate Person
If your cash count reveals a shortage, notify your supervisor or designated employee according to your bank’s procedures.
Don’t wait until you’ve exhausted every possible explanation if your institution requires immediate reporting.
You might say:
“My drawer is showing a $100 shortage. I’ve identified the difference and would like to follow our balancing and review procedures.”
Prompt reporting supports accurate investigation and protects the integrity of the records.
R — Recount Using Approved Procedures
Before assuming a transaction caused the shortage, verify the physical cash count.
Depending on your institution’s procedures, this may involve:
- Separating cash by denomination
- Recounting loose bills
- Verifying strapped currency
- Checking permitted cash compartments
- Having an authorized second employee perform or witness a count
Do not move money between drawers or cash locations to eliminate the shortage.
Some institutions permit additional counts at particular times; others restrict when and how tellers may balance. Follow your bank’s policy.
A — Analyze the Transaction Records
Review authorized transaction records and look for discrepancies that could explain the difference.
For a $100 shortage, you might examine:
- Cash withdrawals involving $100 denominations
- Deposits where the physical count differed from the customer’s stated amount
- Reversals and corrections
- Cash transfers to or from the vault
- Transactions with unusual amounts
- Any documented interruptions or processing issues
The goal is to identify evidence, not simply find a transaction that matches the missing amount.
C — Confirm Before Correcting
Suppose you notice a $900 withdrawal and remember handling ten $100 bills.
That’s worth investigating, but memory alone is not enough to establish what happened.
Work with authorized personnel to review the available records and determine whether a correction is supported.
Never change a transaction merely to make your drawer balance.
An unsupported adjustment can turn an ordinary cash-handling error into a serious record-integrity issue.
Any correction must follow approved procedures, authorization requirements, and audit controls.
E — Escalate, Explain, and Learn
If the shortage remains unresolved, follow your institution’s reporting and escalation process.
Provide a factual explanation of what you’ve checked.
For example:
“My drawer is $100 short. The physical count was verified under our procedure, and we reviewed the relevant transactions. We haven’t confirmed the cause, so I’m documenting and escalating the difference.”
After the investigation, identify one habit you can improve.
The purpose of training is not to pretend mistakes never happen. It’s to build consistent controls that reduce the chance of repeating them.
What If You Find the Exact Mistake?
Let’s return to the $900 withdrawal.
Suppose an authorized review establishes that the customer received $1,000 rather than $900.
You now have a supported explanation for the $100 difference.
That does not mean you should independently debit an account, change the original transaction, contact the customer, or add money to the drawer.
Instead, follow your institution’s approved correction, customer-contact, documentation, and authorization procedures.
The key distinction is:
Finding a likely cause is not the same as having authorization to correct it.
Five Habits That Help Prevent Cash Drawer Shortages
1. Count Cash Without Rushing
A busy line can create pressure to move quickly.
But a few extra seconds of careful counting may prevent a much longer investigation.
Use the counting method approved by your institution.
2. Verify the Amount Before Completing the Transaction
Compare the transaction amount in the system with the amount of cash received or paid out.
If they don’t match, stop and resolve the difference before proceeding.
3. Control Distractions
When permitted by your workflow, complete the current cash-handling step before switching to another task.
If interrupted, restart the relevant verification step rather than relying on memory.
4. Follow Cash Transfer Controls
Vault transfers, teller-to-teller transfers, and other cash movements must be recorded and verified according to approved procedures.
Never assume the physical movement of money automatically updates the system.
5. Report Errors Promptly
If something doesn’t look right, ask for help.
Early reporting gives the institution a better opportunity to preserve accurate information and investigate appropriately.
Three Things You Should Never Do When Your Drawer Is Short
1. Never use your own money to make the drawer balance.
Do not personally replace missing cash to conceal a discrepancy.
2. Never create or alter a transaction without a legitimate, authorized basis.
An unsupported adjustment is not a solution.
3. Never accuse a customer or coworker without evidence.
A cash difference requires investigation, not speculation.
Your responsibility is to report accurately, preserve records, and follow the approved process.
Teller Tuesday Knowledge Check
Your teller drawer is $100 short.
You remember a customer who withdrew $900 earlier, and you suspect you might have given them $1,000.
What should you do first?
A. Change the withdrawal to $1,000 so the drawer balances.
B. Put $100 of your own money into the drawer.
C. Report the shortage, verify the count, and investigate the transaction using approved procedures.
D. Call the customer and demand that they return $100.
Correct Answer: C
The amount and your memory provide a possible lead, but they don’t prove the cause.
Always verify and follow the appropriate reporting and investigation procedures before any authorized correction.
Frequently Asked Questions About Teller Cash Shortages
What should a bank teller do when their drawer is short?
Notify the appropriate supervisor, verify the physical count, review authorized records, document the discrepancy, and follow the institution’s investigation procedures.
What causes a teller drawer to be $100 short?
Possible causes include overpaying a withdrawal, overstating a cash deposit, miscounting currency, or incorrectly recording a cash transfer. The amount alone doesn’t establish the cause.
Can a teller get fired for a cash shortage?
Employment consequences depend on the institution’s policies, the circumstances, the employee’s history, and applicable employment rules. No one can determine the outcome from the shortage amount alone.
Should a bank teller pay back a cash shortage?
Tellers should not personally replace missing cash to conceal a discrepancy. Any questions about employee liability or reimbursement should be addressed through the institution’s HR, legal, and compliance procedures and applicable law.
How often should a teller balance their cash drawer?
Balancing frequency varies by institution. Some require particular checkpoints; others limit balancing to designated times. Follow your institution’s approved procedures.
What is force balancing in banking?
The term generally refers to improperly making cash or records appear balanced without a legitimate, authorized correction. Practices and definitions can vary by institution, so employees should follow their bank’s specific policies.
Your Teller Tuesday Challenge
Before your next shift, review these questions:
- Do I know my bank’s required balancing process?
- Do I know whom to notify about a shortage?
- Am I following the approved cash-counting method?
- Do I know which corrections require authorization?
- Am I documenting discrepancies accurately?
If you can’t answer one of these questions confidently, ask your supervisor or trainer.
Good tellers don’t rely on luck to balance their drawers. They rely on consistent procedures, accurate records, and sound judgment.
Keep Building Your Bank Teller Skills With Jay Get It
Cash handling is only one part of becoming a confident banking professional.
Jay Get It helps banking professionals strengthen practical skills through banking training, professional tools, and financial education.
Explore free bank teller training resources and checklists:
https://jaygetit.com/free-resources
Your Teller Tuesday takeaway:
When your drawer is short, don’t panic, guess, or hide the difference.
TRACE: Tell. Recount. Analyze. Confirm. Escalate.
Jay Get It — Know It. Apply It. Get It.
Educational disclaimer: This article provides general banking training information. It is not institution-specific operational, legal, or compliance advice. Employees should follow their bank’s current policies, approved cash-handling procedures, supervisory instructions, and applicable laws.

