
Banker Monday | Jay Get It — Practical Banking Training
A customer walks into your bank and deposits a $2,500 check.
A few minutes later, they look at their account and discover they cannot access all the money.
They return to your desk, frustrated.
“That’s my money! Why is the bank holding it?”
You understand that check holds are part of banking. But knowing the policy and explaining it to an upset customer are two different skills.
For bank tellers and personal bankers, this situation creates a common challenge: How do you explain a check hold clearly, protect the customer’s trust, and follow your bank’s procedures?
Today, we’re breaking down a practical approach you can use.
Why Do Banks Place Holds on Checks?
A check deposit does not always mean the full amount is immediately available for withdrawal.
A bank may need to verify or collect funds, manage the risk of a returned check, or apply a permitted exception under its funds-availability policy.
Depending on the circumstances, factors may include:
- The type and amount of the check
- How and when the deposit was made
- The account’s history and status
- Whether an applicable exception permits a longer hold
- The bank’s disclosed funds-availability policy
In the United States, Regulation CC establishes important funds-availability requirements for covered check deposits. Banks may make funds available sooner than required, but employees should never guess about a particular customer’s availability date.
Important: The exact reason for a hold and the date funds become available must be verified using the bank’s approved systems, disclosures, and procedures.
The Mistake Bankers Make When Explaining Check Holds
Imagine responding to the customer with:
“It’s bank policy. There’s nothing I can do.”
That response might feel efficient, but it does not answer the customer’s real questions:
- Why can’t I use my money?
- When will it become available?
- What am I supposed to do now?
A better approach is to explain what you can verify, acknowledge the inconvenience, and identify the next appropriate step.
You do not need to promise an exception or override a hold to provide helpful service.
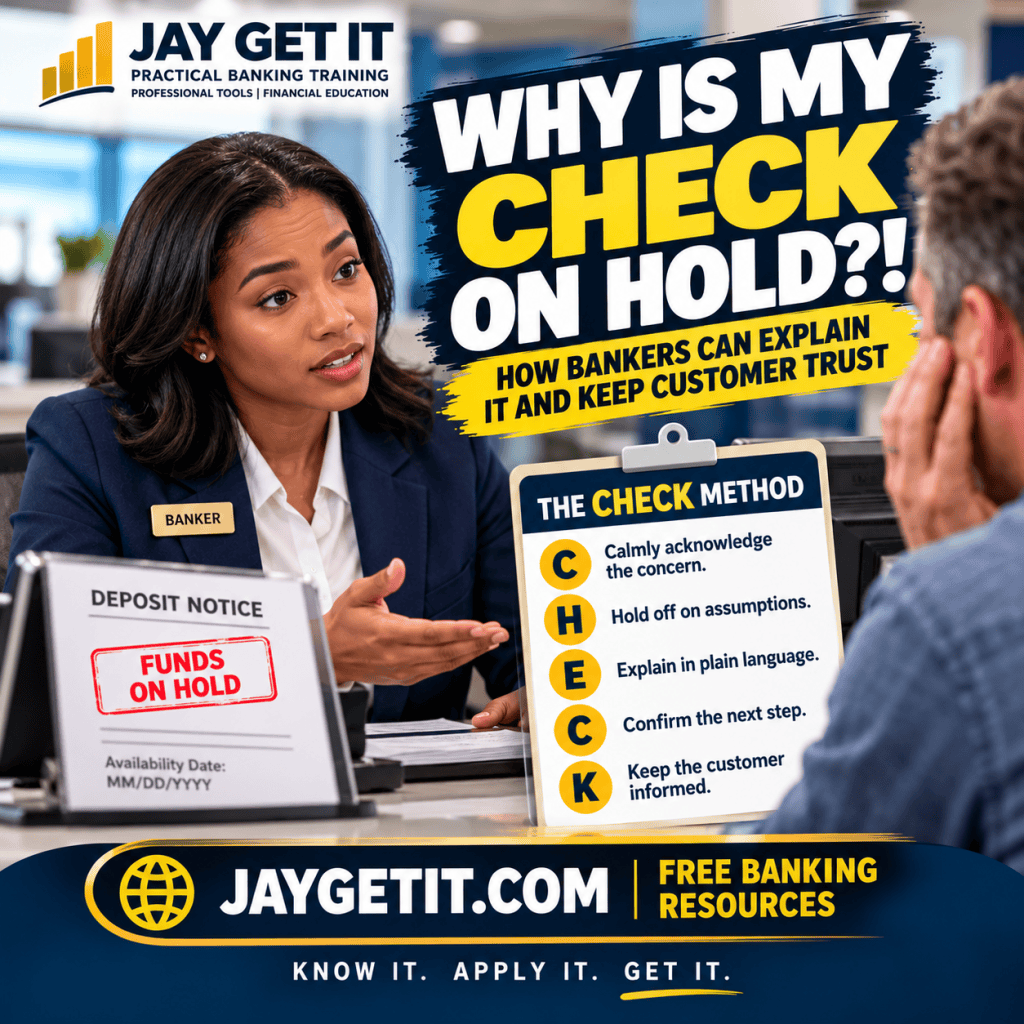
The 5-Step CHECK Method for Explaining a Deposit Hold
Here’s a practical framework for handling these conversations.
C — Calmly Acknowledge the Concern
Start by recognizing the customer’s frustration.
Try saying:
“I understand why that’s frustrating, especially if you were planning to use those funds today. Let me review the deposit information so I can explain what we’re seeing.”
This communicates that you are taking the concern seriously without promising a result.
H — Hold Off on Assumptions
Before explaining the hold, check the relevant account and deposit information using authorized systems.
Verify:
- Which deposit the customer is asking about
- Whether a hold is actually in place
- The recorded availability date
- Any approved explanation or notice associated with the hold
Do not assume every hold exists for the same reason.
If you cannot determine why the hold was placed, follow your institution’s escalation process rather than inventing an explanation.
E — Explain in Plain Language
Avoid unnecessary banking jargon.
Instead of:
“The item is subject to an exception hold under our funds-availability schedule.”
Try:
“Your check was accepted for deposit, but some of the money isn’t available to withdraw yet. Let me explain the availability date shown for this deposit.”
If the reason is verified and approved for disclosure, explain it accurately.
Keep the explanation simple, specific, and consistent with your institution’s policy.
C — Confirm the Next Step
The customer wants to know what happens next.
Explain the verified availability information and any options your bank permits you to discuss.
For example:
“Our system shows the funds are scheduled to become available on [verified date]. If you’d like, I can explain the information on your deposit notice.”
If the customer asks whether the hold can be released early, do not guarantee that it can.
Instead, explain whether your institution has an approved review or escalation process.
K — Keep the Customer Informed
Before ending the conversation, make sure the customer understands the explanation.
Ask:
“Does that help clarify when the funds are expected to be available?”
If the issue remains unresolved, document the interaction and arrange any appropriate follow-up under your bank’s procedures.
Remember: A good explanation may not eliminate the customer’s frustration, but it can reduce confusion.
Example: A Better Check-Hold Conversation
Customer: “I deposited my paycheck. Why can’t I use my money?”
Banker: “I understand your concern. Let me review the deposit and its availability information.”
The banker verifies the details using the institution’s approved system.
Banker: “I can confirm the deposit was accepted. The system shows that part of the deposit is not available yet, with an availability date of [verified date].”
Customer: “But I need that money today!”
Banker: “I understand that the timing is important. I don’t want to promise something the bank hasn’t approved. I can explain the hold information and check whether an authorized review process is available.”
Customer: “So what should I do?”
Banker: “Let’s review the verified next steps together so you know what to expect.”
Notice what the banker did:
- Acknowledged the customer’s concern
- Checked the facts before responding
- Explained the situation clearly
- Avoided promising an early release
- Offered an appropriate next step
That’s the difference between repeating a policy and helping a customer understand it.
What Bankers Should Know About Regulation CC
For U.S. banks, Regulation CC is an important part of funds-availability training.
As of October 2026, certain Regulation CC dollar thresholds were updated effective July 1, 2025. For example, the minimum next-business-day availability amount for certain covered check deposits increased to $275, and the large-deposit exception threshold increased to $6,725.
These figures are not universal promises that every deposited check will be available on a particular day. Deposit types, timing, applicable exceptions, and institutional policies matter.
Bankers should consult current official requirements, their institution’s disclosures, and compliance-approved training materials.
Official reference: CFPB — Regulation CC Threshold Adjustments
Three Things You Should Never Say About a Check Hold
1. “Your money will definitely be available tomorrow.”
Unless you have verified that information, don’t promise it.
2. “The bank can hold any check for as long as it wants.”
That’s misleading. Applicable funds-availability rules and bank policies establish requirements and limits.
3. “I’ll remove the hold for you.”
Never promise an action you are not authorized to perform.
The better habit: Verify first. Explain clearly. Escalate appropriately.
Banker Monday Practice Challenge
A customer deposits a check and says:
“I’ve been banking here for ten years. Why are you holding my check?”
Which response is best?
A. “Everyone gets holds. It’s just our policy.”
B. “You’ve been a customer for ten years, so I’ll release it.”
C. “I understand your concern. Let me review the deposit details, explain the availability information, and check what options are available under our procedures.”
Correct answer: C.
A customer’s history may be relevant to the bank’s policies, but it does not justify making promises or bypassing approved controls.
Frequently Asked Questions
How should a bank teller explain a check hold?
Start by acknowledging the concern, verify the deposit and hold information, explain the confirmed availability date in plain language, and identify the next authorized step.
Why is my check on hold after I deposited it?
A hold may relate to funds-availability rules, the deposit’s characteristics, account circumstances, or an applicable exception. The bank should provide the relevant availability information and any required notices.
Can a bank release a check hold early?
An early release may be possible in some circumstances, depending on the institution’s procedures and authorization requirements. Frontline employees should never promise an exception without approval.
What should a banker do when a customer becomes angry about a hold?
Remain professional, listen without interrupting, verify the facts, avoid unsupported promises, and involve an authorized supervisor when necessary.
Does Regulation CC apply to every type of deposit in the same way?
No. Different deposit methods and payment types can be subject to different rules. Mobile deposits, for example, may have different availability arrangements from covered in-person check deposits.
Keep Building Your Banking Skills With Jay Get It
Explaining a check hold is only one of the many situations banking professionals face.
The same core skills apply to transaction questions, account concerns, difficult customer conversations, and everyday branch operations.
At Jay Get It, our focus is practical banking training, professional banking tools, and financial education.
Explore our free resources and continue strengthening your skills:
Explore Free Banking Training Resources →
Your Banker Monday takeaway:
Don’t guess. Don’t overpromise. Don’t hide behind jargon.
CHECK: Calmly acknowledge. Hold off on assumptions. Explain. Confirm. Keep informed.
Know It. Apply It. Get It.
Educational disclaimer: This article provides general banking education and is not legal or institution-specific compliance advice. Banking professionals should follow their institution’s current policies, approved procedures, applicable regulations, and legal/compliance guidance.

